 SHARPE
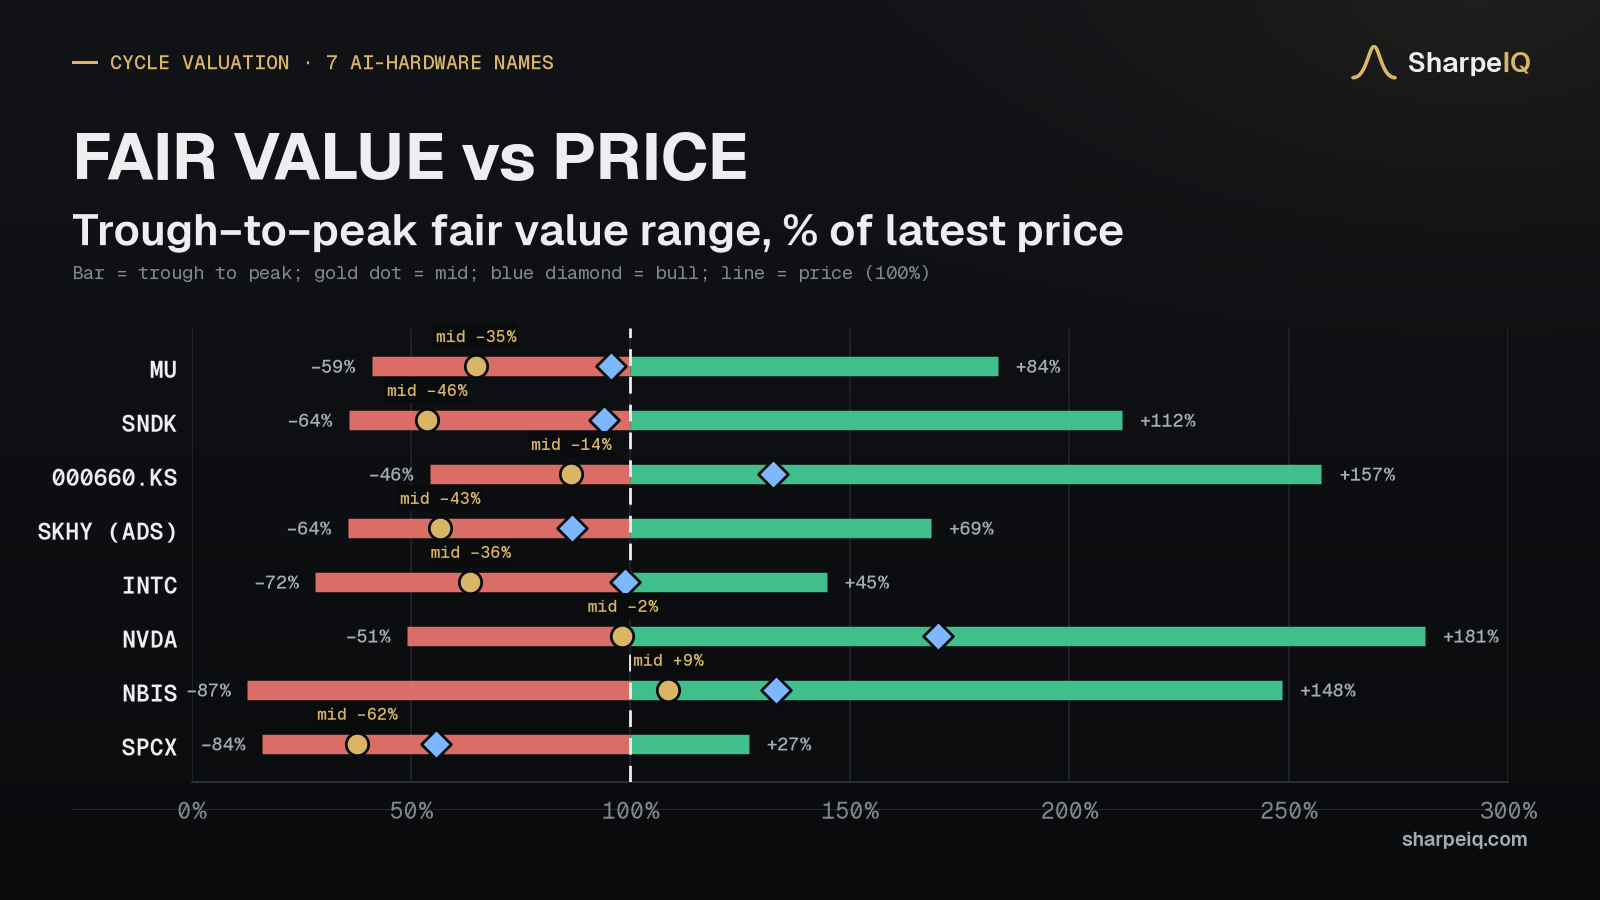
SharpeIQ Research, 18 November 2026, after NVIDIA Q3 FY27 earnings. Prices: US names at the last extended-hours print on 17 Nov (8pm ET, after the print). SK hynix (000660.KS) at the KRX quote on 18 Nov, 11:11 SGT. FX ₩1,331/$ (11:31 SGT). The full price table is below.
Summary
- We now run four cases. Mid assumes normalization starts in FY28 (CY28 for SK hynix, NVDA FY29, NBIS/SPCX 2028–29). Bull is our previous mid: contracted pricing holds through FY28. On that basis the mid case is below the price for MU, SNDK, 000660.KS, INTC, NVDA, SPCX and above it for NBIS. MU and SNDK trade close to bull value (bull −4% / −6%), so the price already assumes LTAs hold for two more years.
- Backlog is not cash. MU’s $150bn RPO and SNDK’s $91bn backlog are floor-priced volume commitments. SNDK holds $2.5bn of cash deposits against them (2.7%). In the last bust, margins turned negative within one fiscal year: MU FY23 −37.0%, and SK hynix 2023 −23.6% (from +15.3% in 2022). Our mid cases credit contracted cash for FY27 only.
- The average trough case is −66% from here. Troughs still credit 12–24 months of contracted cash flow. The losses come from normalising to through-cycle margins (MU FY10–25 median operating margin 18.6%; SK hynix 2018–25 median 22.3%).
MU, SNDK and SK hynix fair value: what changed after NVIDIA’s print
- SK hynix holds up best of the memory names: mid −14%, bull +33% on the KRX line. The Nasdaq ADS (SKHY, $129.61) trades at a +53% premium to KRX. On the ADS the same mid case is −43% and bull −13%.
- NVDA mid −2% and NBIS mid +9% assume AI-capex digestion from 2028. Both need bull (+70% / +33%) for real upside. SPCX at $143.37 is above its bull case. The price implies about 30x 2028E EBITDA on SI, using our mid-case values for the other segments.
- NVDA Q3 FY27 beat on every line: revenue $115.8bn vs $109.1bn, Q4 guide $130bn vs ~$125bn. NVDA’s fair values rise to $80 / $160 / $277 / $458. Supply commitments rose to $390bn, mainly multi-year memory procurement. That supports the HBM/DRAM backlog at SK hynix and MU, but not NAND. Receivables, inventory and $118bn of guarantees are the late-cycle flags.
- Catalysts: SNDK 8-for-1 split (trades split-adjusted from 20 Nov), the start of MU’s $35.16bn buyback (9 Dec), and NVDA’s CEO search (Kress interim).
These cases sit next to our Micron DCF, the October memory unwind, MU and Sandisk implied vol, SpaceX Q2 results and SPCX implied vol after the IPO.