 SHARPE
SharpeIQ Research Desk · IPO Watch · 11 Nov 2026 · data: SEC S-1/A No. 2 (10 Nov 2026), SharpeIQ settled closes to 10 Nov 2026
Abstract (free preview)
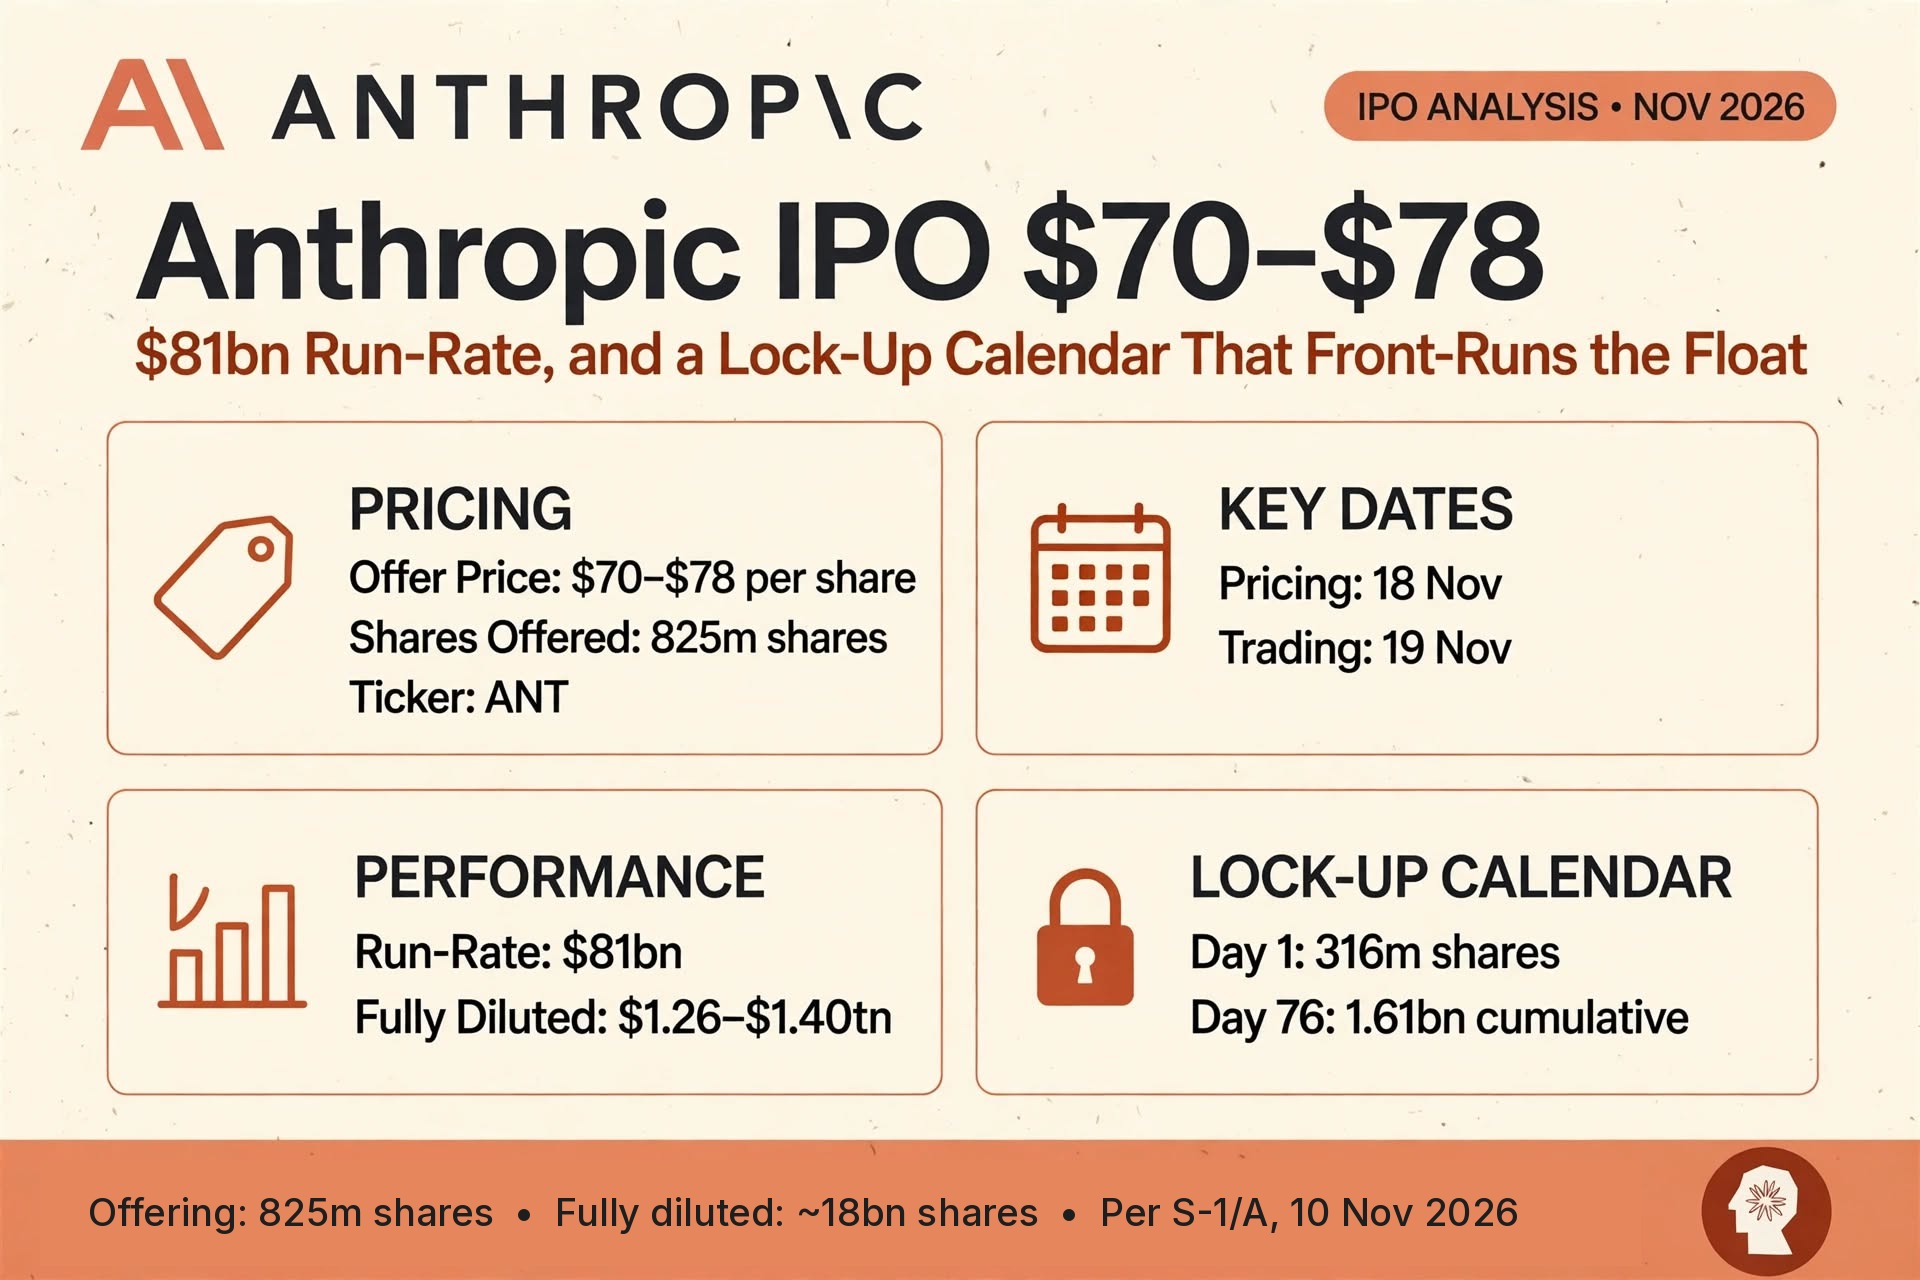
Two weeks ago the Anthropic S-1 had blanks where the deal should be. Amendment No. 2, filed 10 Nov, fills them: 825m Class A shares at $70–78 (801.4m primary, 23.6m secondary), a 123.75m-share greenshoe, and a $26bn concurrent Class N placement at the IPO price to Google ($10bn), NVIDIA ($10bn), AMD ($2.5bn), Broadcom, Micron, Microsoft ($1bn each) and TSMC ($0.5bn) (S-1/A). That prices ANT at ~$1.26–1.40tn fully diluted (CNBC, TechCrunch) — below the $1.5–2tn whispered in October — against a newly filed $81bn run-rate revenue at 31 Oct. Pricing is targeted for 18 Nov, first trade 19 Nov (reported, not filed). The book was covered on day one and the FT reports bankers weighing a move above the range to $1.5tn+ (unconfirmed).
Our read: on run-rate, ANT is being offered at 15.6–17.3x — cheaper than SPCX at listing (~95x FY25 revenue) and in line with ARM’s ~20x, for a business growing revenue ~12x y/y. The trade is not the multiple. It is the float mechanics: 316m shares are unlockable on day one, and early releases reach up to 1.61bn cumulative by day 76 (≈2x the IPO base, early February; tranche sizes after day 1 are filing-derived, S-1/A pp. 318–319).
Key takeaways · 15-second read
- Terms are set. $70–78, 825m shares, $57.75–64.35bn base; up to ~$100bn including shoe and the $26bn strategic placement.
- Valuation came in, not up. $1.26–1.40tn FD vs $1.5–2tn reported in October; the $965bn Series H (May) is now in the filing.
- Fundamentals beat the whisper. Q3 revenue $17.0bn (derived: 9M less H1) vs $16.8bn reported; run-rate $81bn, +$10bn in October alone.
- Compute bill is now a number: $900.9bn committed, $451.6bn of it before end-2030.
- Supply calendar is the vol catalyst: day-1, day-27, day-48, day-62, day-76 tranches before the FY26 print unlocks up to 1.7bn more.
Desk verdict (full playbook below): don’t chase the open; sell IV once options list; buy into the day-27 to day-76 lock-up tranches when supply peaks.